Some days stretch into weeks, and some weeks barely last a day.
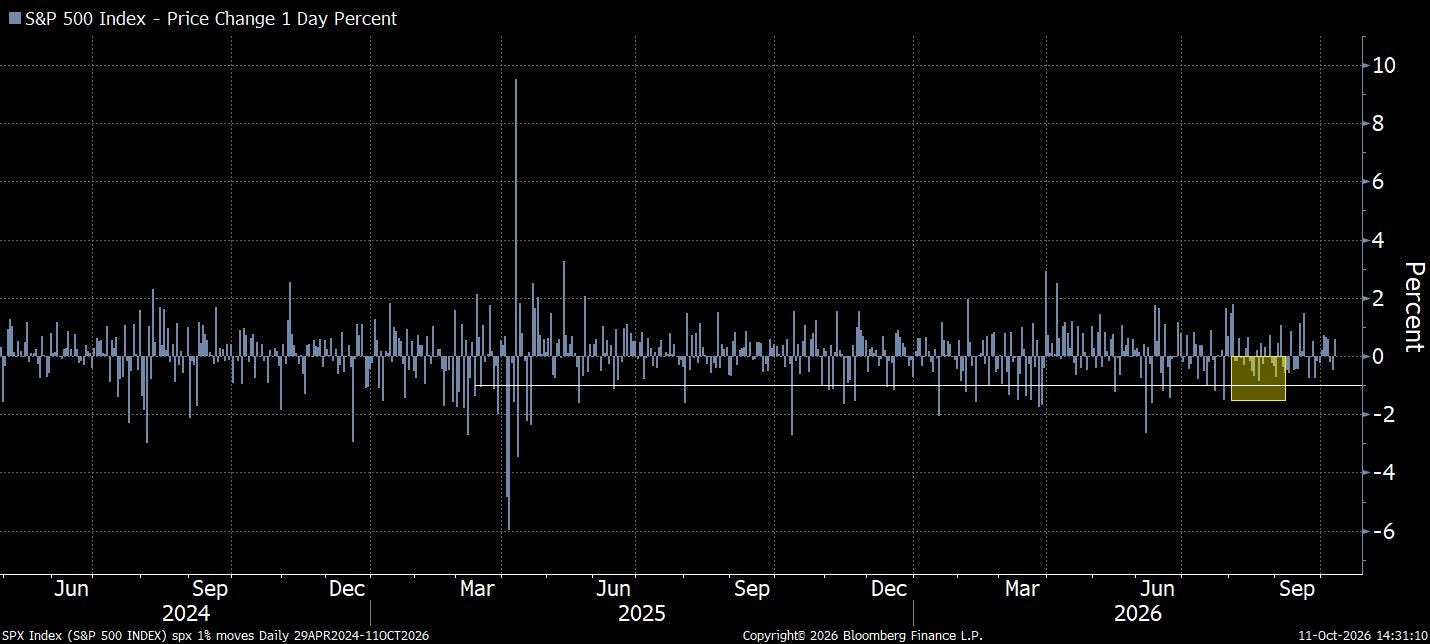
Last week felt slow. Stocks ticked to new highs on Tuesday but lacked the impetus seen in earlier highs this year. As little surprise, the move was driven by AI spending. Thursday saw stocks drop after the FT reported that OpenAI is on track to generate annualised revenue of roughly $50bn based on its current performance. Yet risk-on spirits returned the following day, Friday, with the Spoos and Qs both settling the week at highs. The S&P 500 is in its longest streak of calm since July 2024, with no 1% down day in 49 straight sessions.
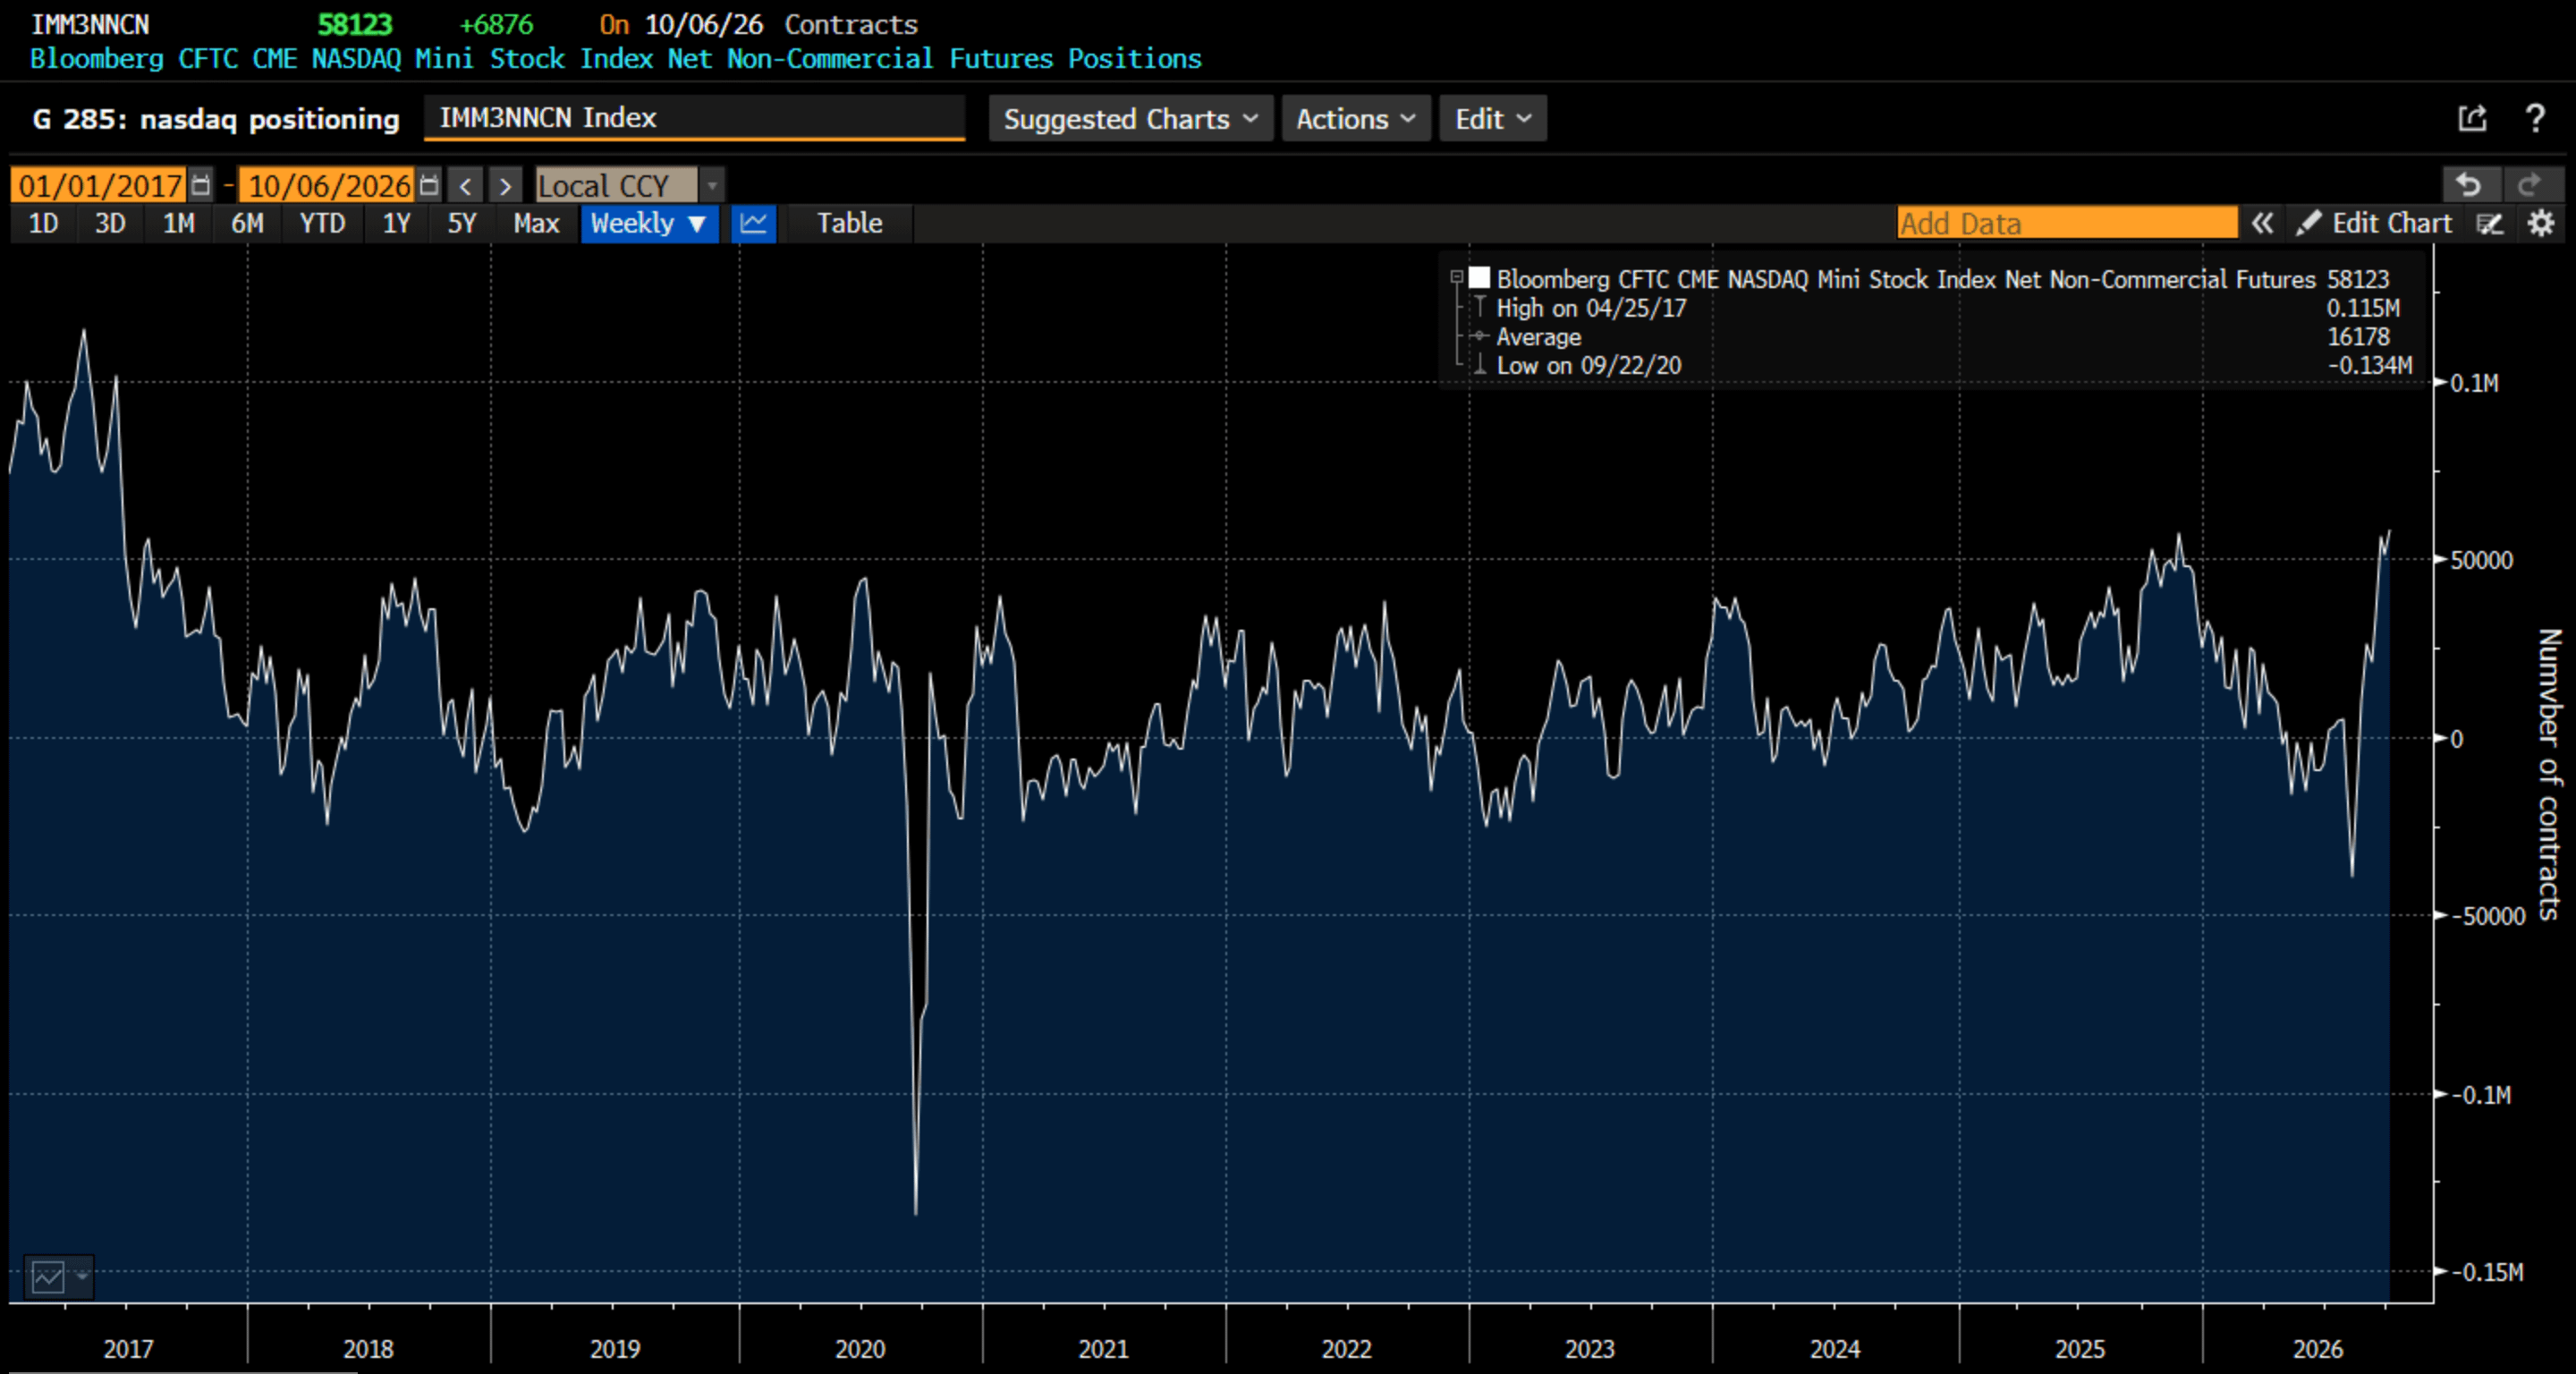
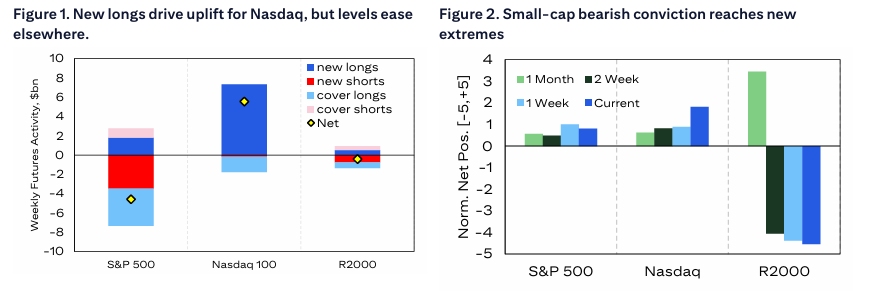
Per CFTC data, hedge funds have boosted long positions in Nasdaq 100 futures to their highest levels since 2017. The tech bias is also reflected in Citigroup’s analysis.
Yields remained the centre of attention, though they brought far less drama than in recent weeks. Midweek auctions for 10-year and 30-year Treasuries saw particularly strong demand, suggesting lofty yields are starting to entice some buyers. That helped spark a brief relief rally, with the 10-year falling as low as 5.22% and the 30-year touching as low as 5.59%. To us, US 10s and 30s look set to roll over further. Debt stress remains more pronounced in Europe, with OAT- and BTP-Bund spreads widening again into the week’s end, despite some initial relief from Le Pen’s fiscal plans.
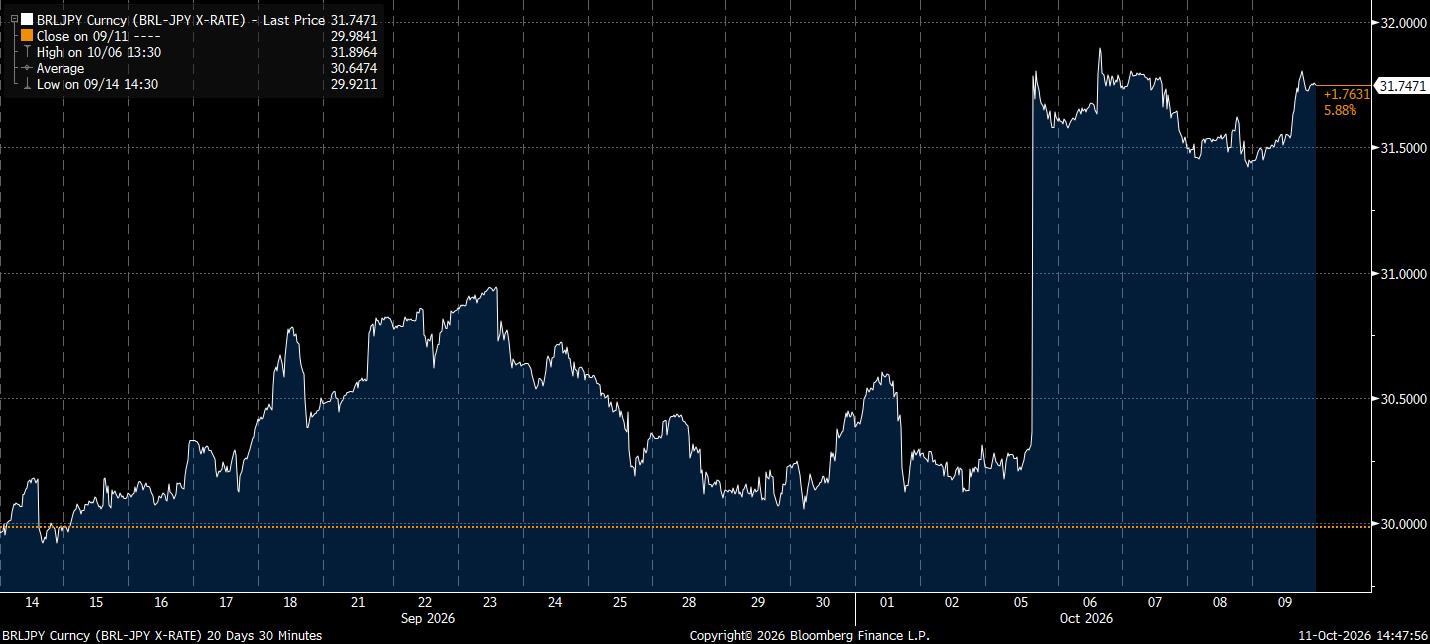
The dollar is in its longest run of strength since January 2025, driven by safe-haven demand amid Middle East conflict and a selloff in European sovereign debt. But the big currency story (and overall market mover) was Brazil. Brazilian markets rallied after the October 4 vote on expectations that right-wing Senator Flavio Bolsonaro will win the October 25 runoff and deliver a much-needed fiscal adjustment to stabilise Brazil’s high and rising public debt. His chances of victory look palpable; his plans for fiscal adjustment, less so. The Brazilian real was up 5% against the yen in Monday’s session.
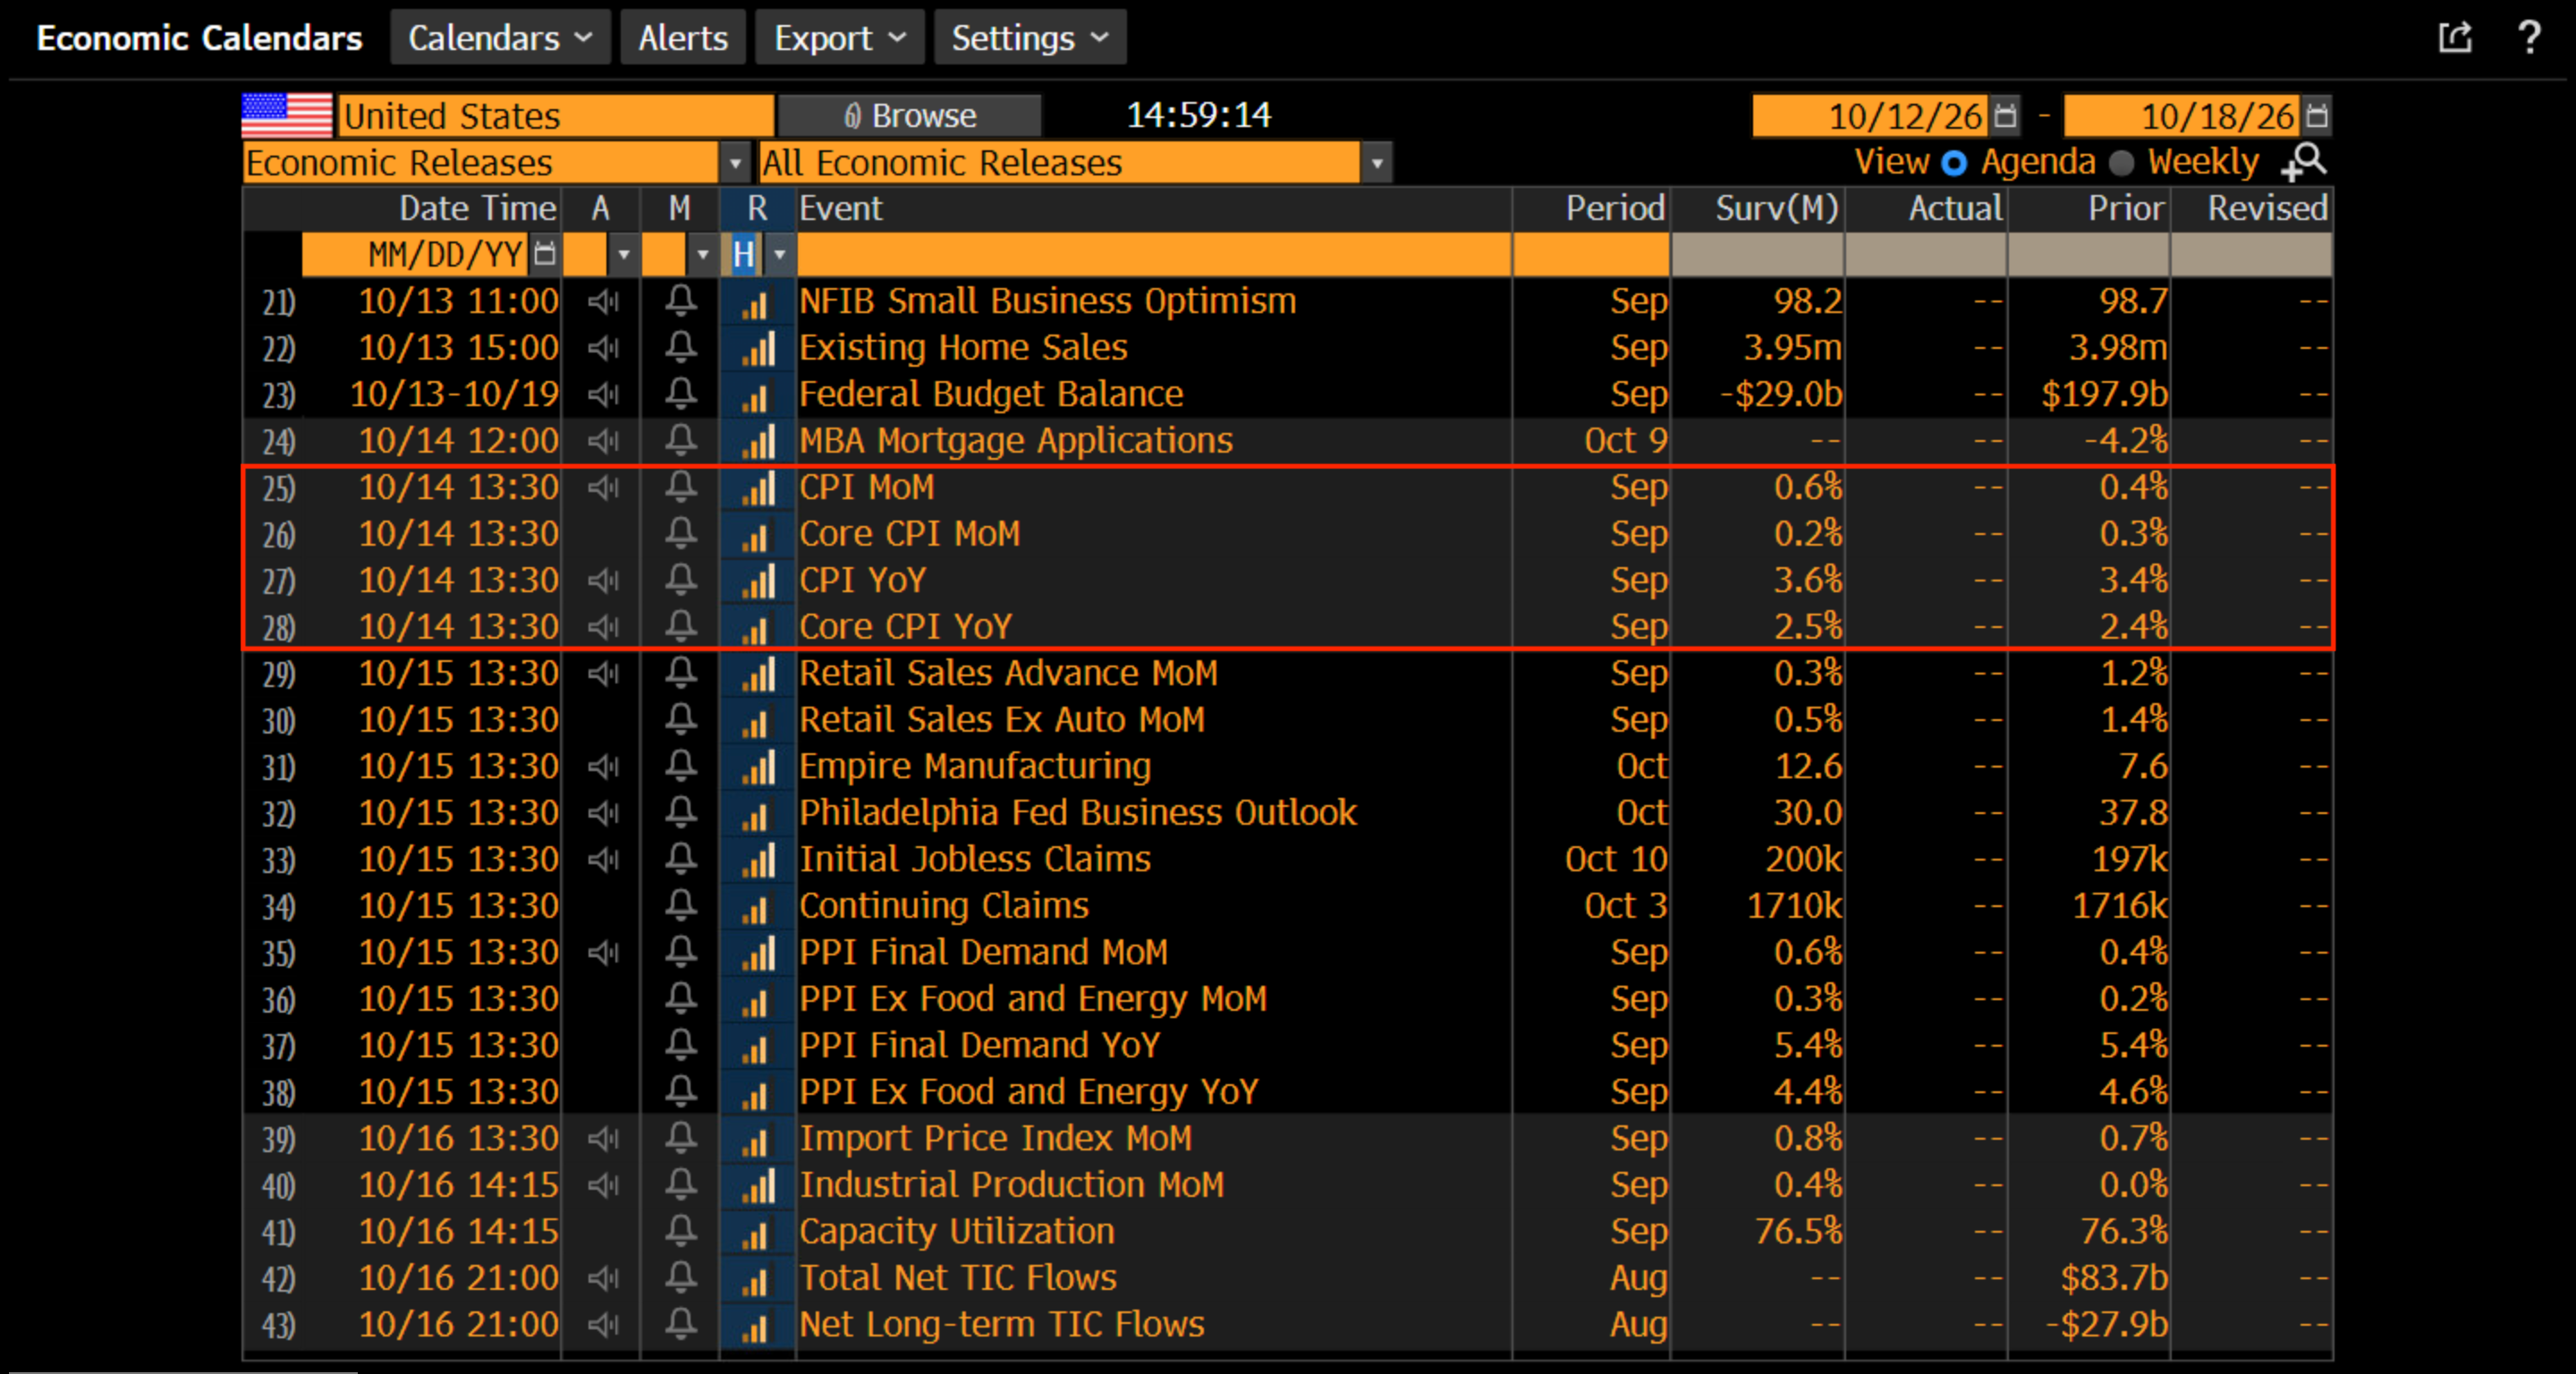
However, the real test this week is US CPI, which may help or hinder the Fed’s hand, and a big test for stocks arrives, with banks including JPMorgan Chase, Goldman Sachs, and Citigroup kicking off the earnings season. Any signs that higher yields are not severely weakening credit quality and borrower health will be a welcome reprieve for the KBW Bank Index, which has declined for five consecutive weeks and is down 12% from a record.
That wraps up what felt like a quieter week in markets before an important few days ahead. Let’s get into the guide to trades moving markets, where things stand, and where they may be heading.
“CPI Game-plan”
“Watch the Dispersion Trade”
“Summary of House Views”
For newer readers, or those who have yet to explore the full AP Research offering, our about page is a useful place to start. It outlines what we publish, how we approach markets, and how we translate our research into actionable investment views. If you’re considering full access, we encourage you to take a look. We also offer trial access for those who would prefer to see the research first.
CPI Game-plan