
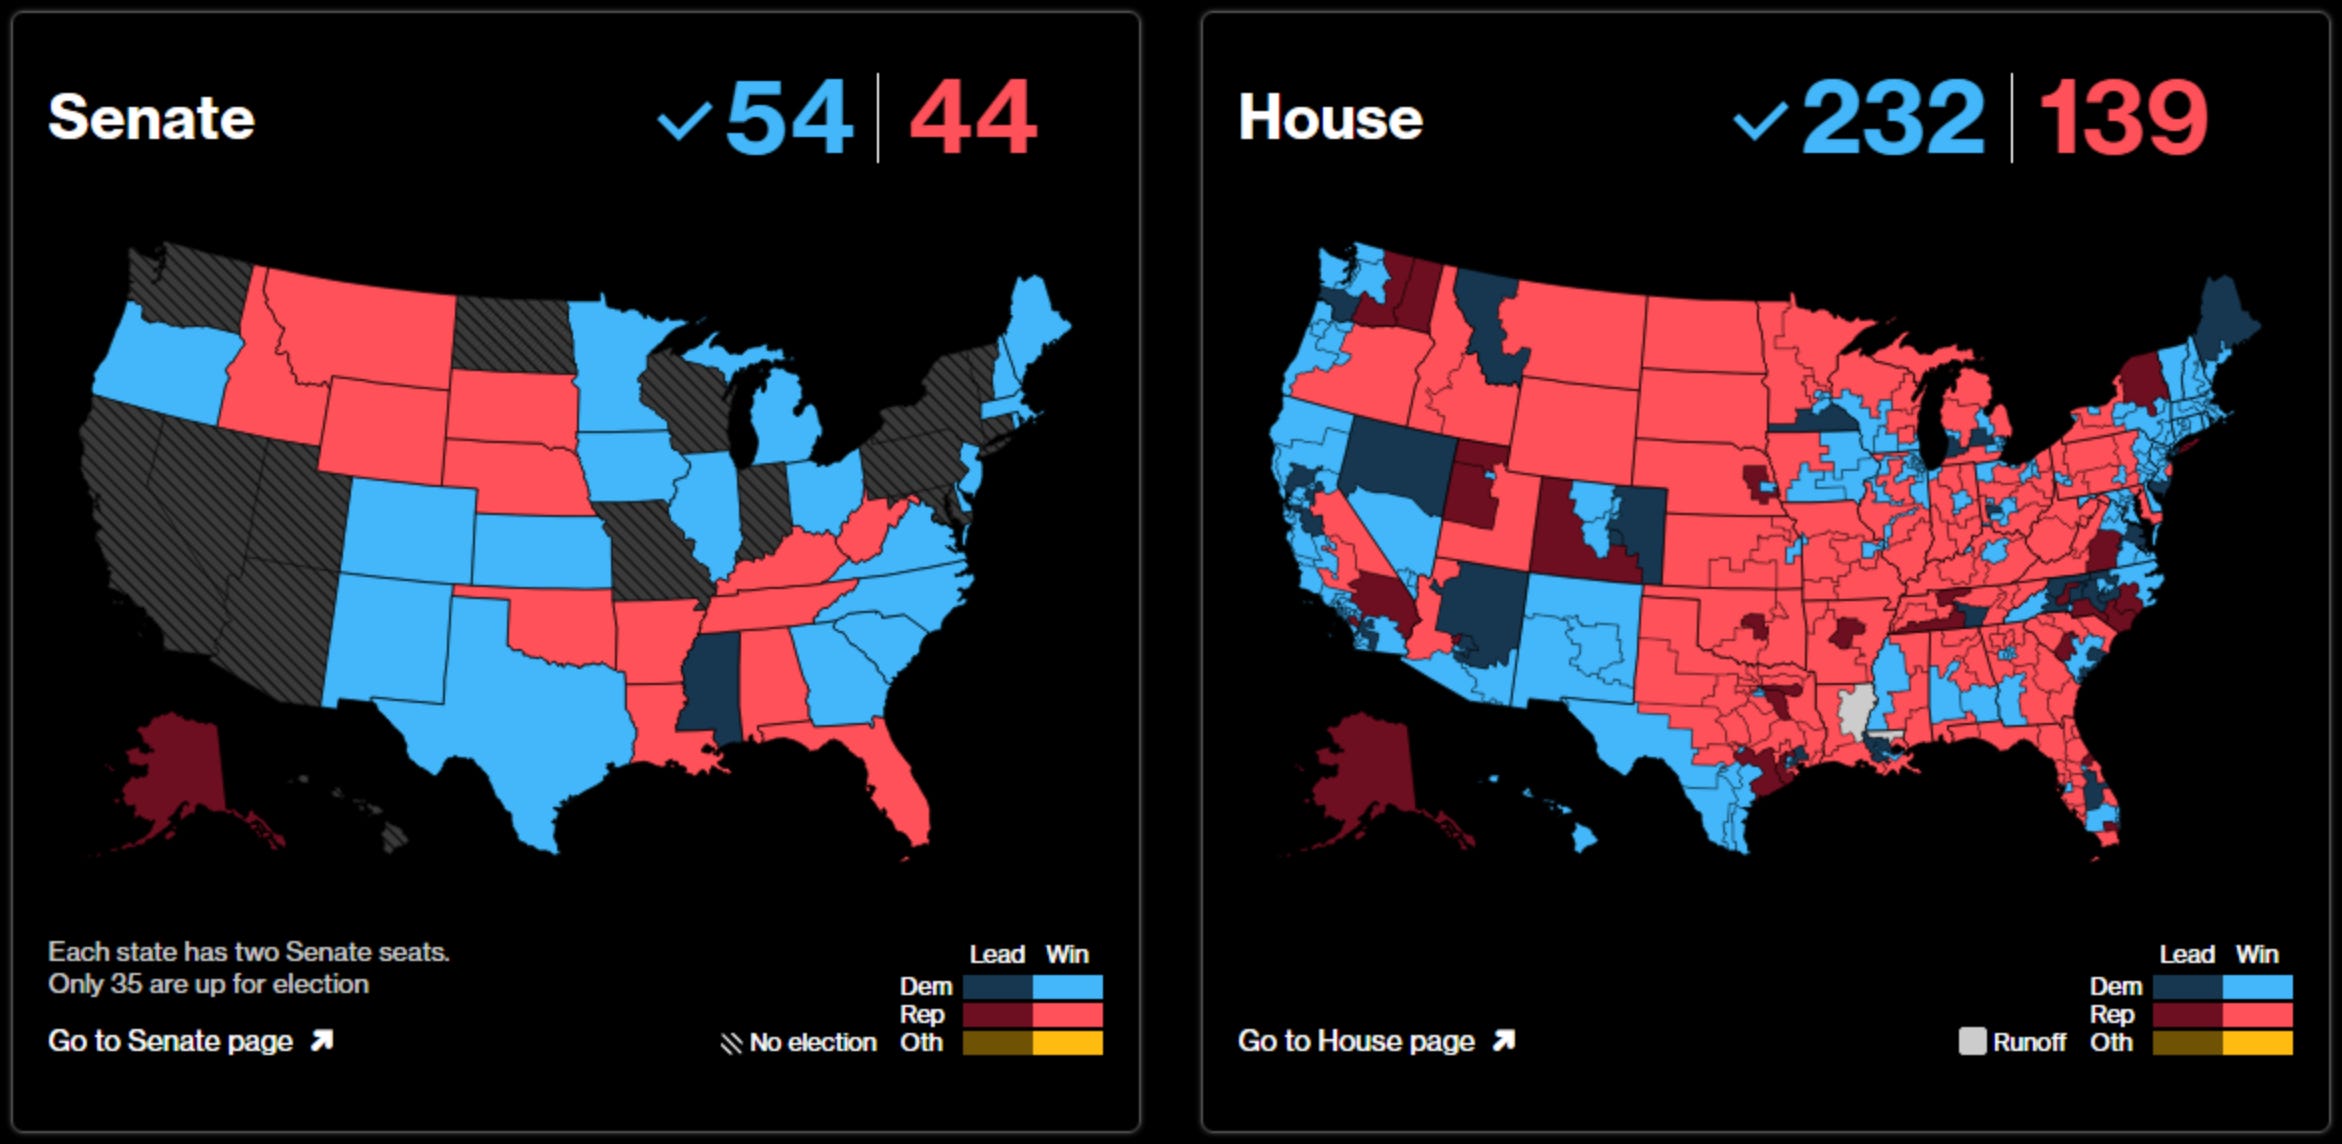
As Europe rose and the US ended a late night, it looked clear that a Blue Tsunami was hitting markets.
Riding an overwhelming tide of voter angst, Democrats swept into power in Congress, with outrage over the war in Iran and the cost of living leading to a thundering rebuke of President Donald Trump and his party just two years after his dominant White House comeback.
Markets moved quickly to reflect the Democratic sweep, with equities and crypto lower, yields falling, and the dollar the standout asset under pressure. A Democratic Congress could challenge the US Exceptionalism story over time, particularly if any policy affects AI investment and growth, but the here-and-now narrative still stands: The US still has the strongest investment story among peers. As such, many of the knee-jerk reactions have started to reverse.
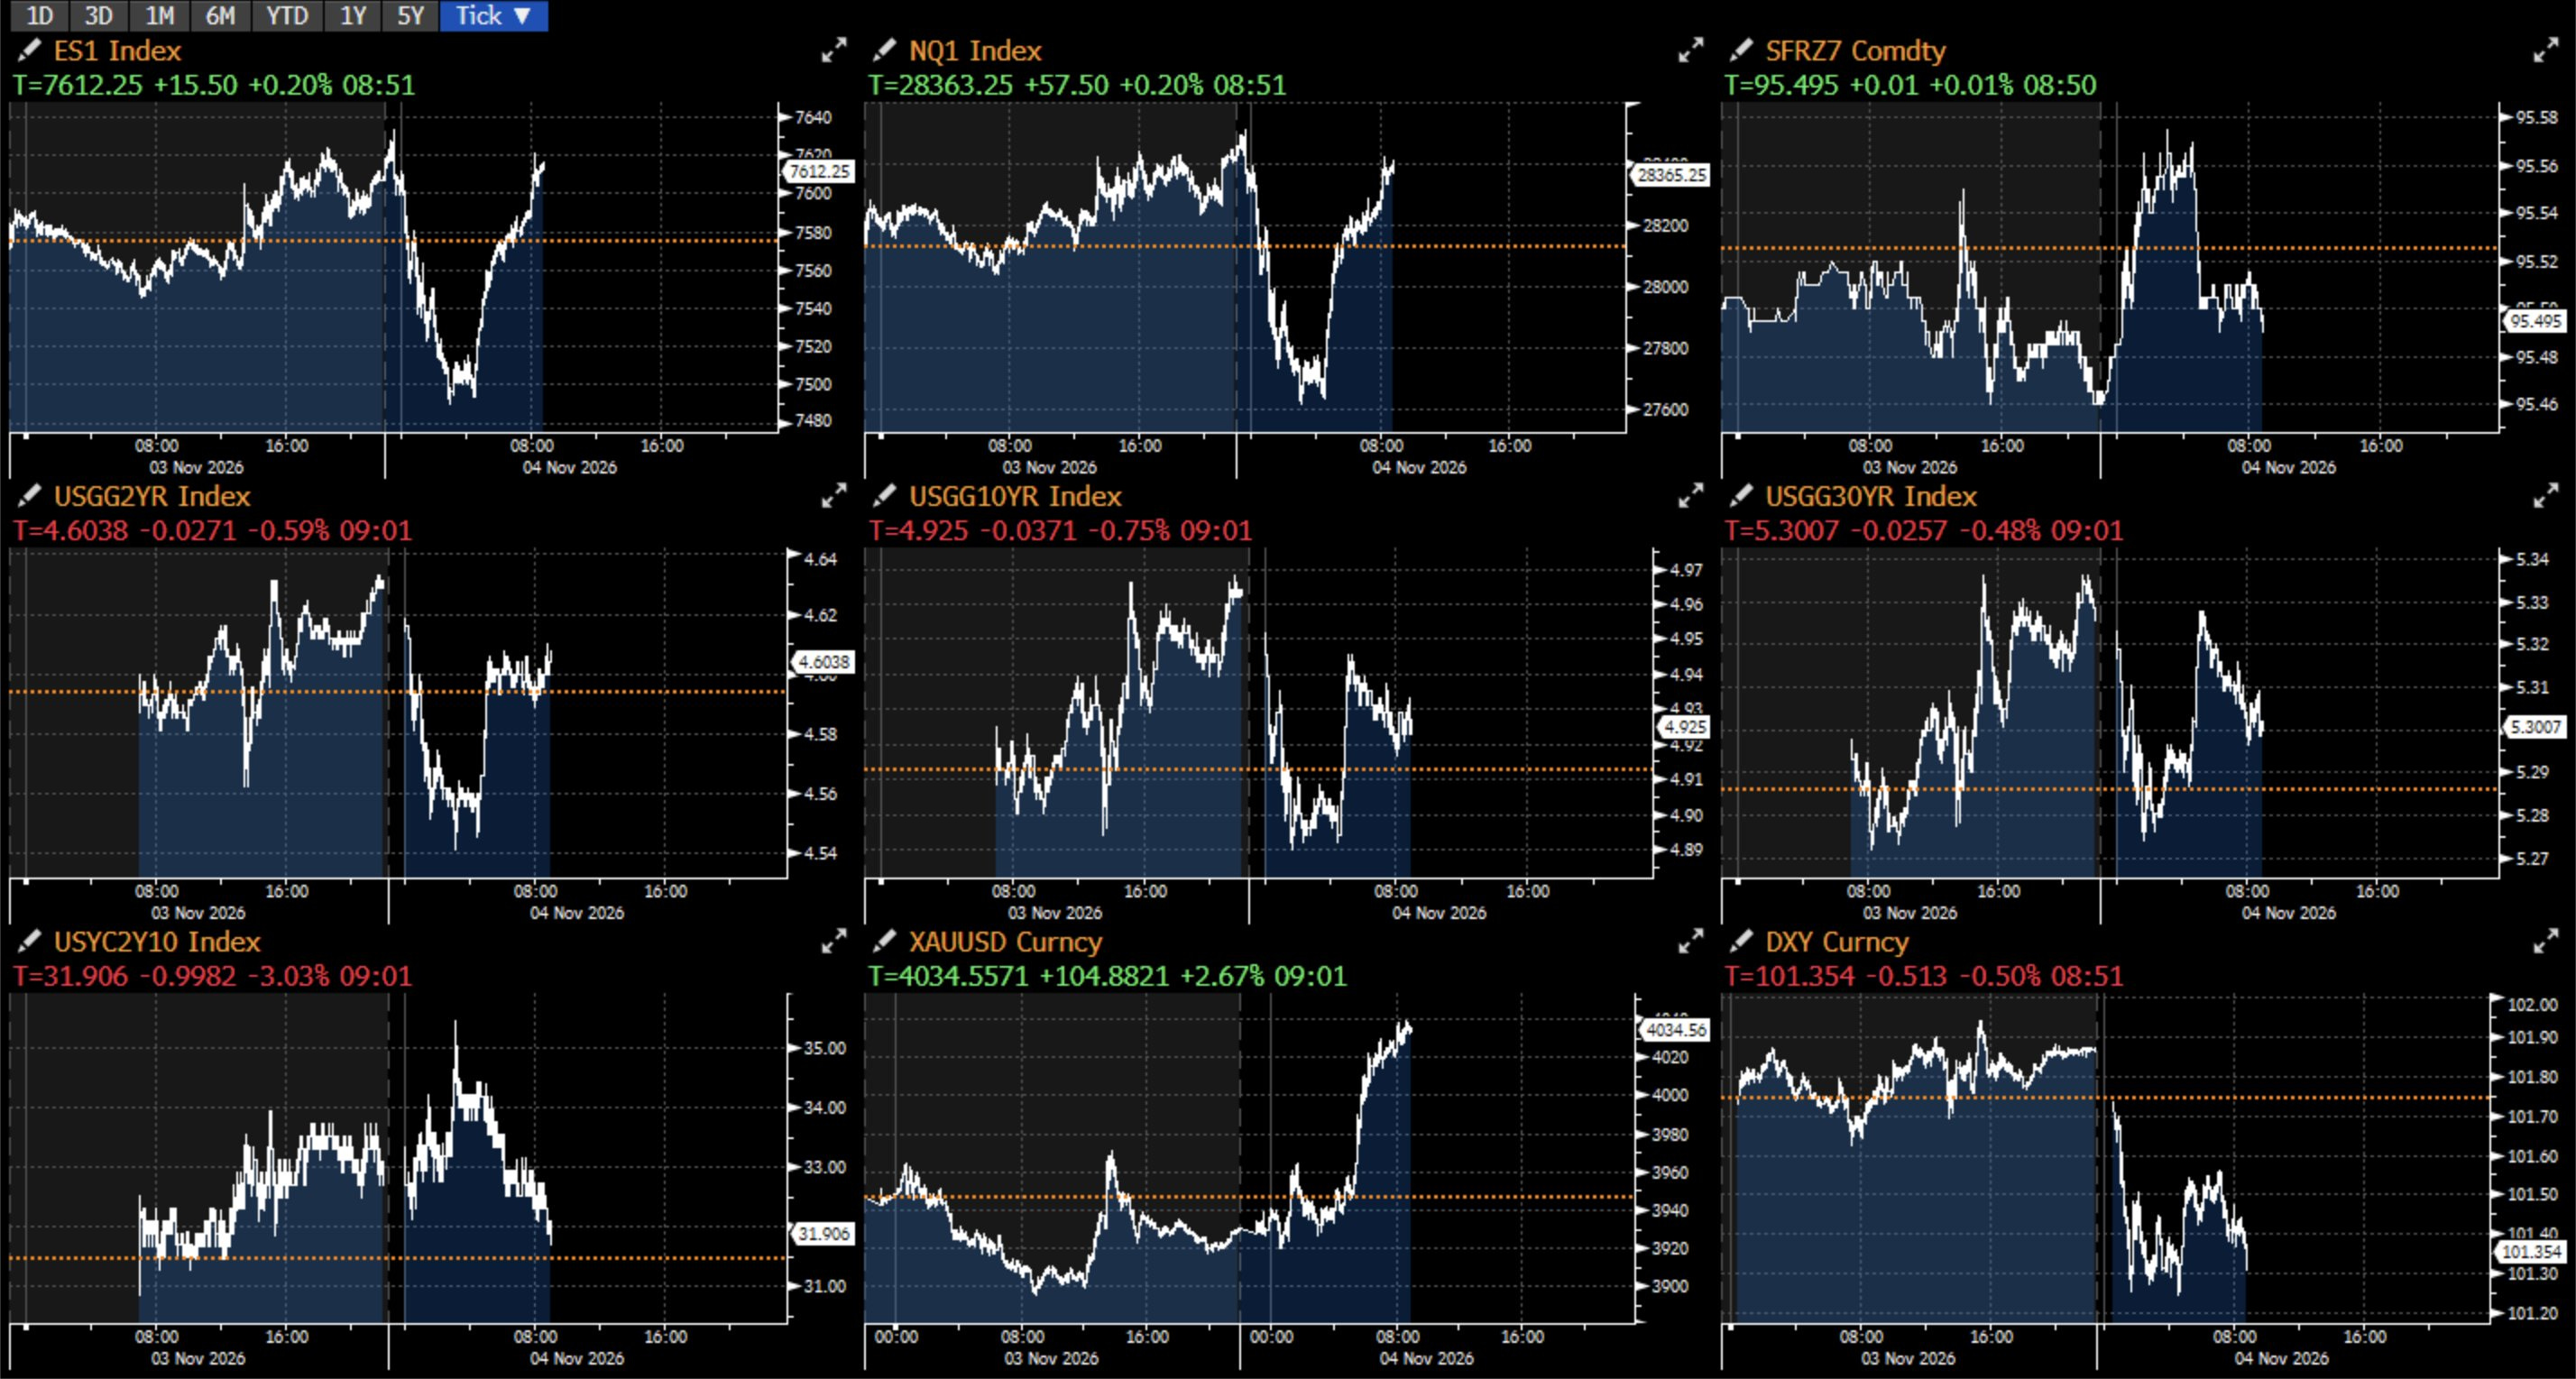
There are some notable moves to share, some of which we believe will extend and some to reverse.
So, a cross-asset note was required, with thoughts on FX, equities, yields, oil, and gold/bitcoin below.
Dollar and Peers
Yesterday morning, ahead of election results, our team on APFX posted the memo “Musing the Midterms”, noting under the scenario of a Democratic sweep that “FX markets… would expect modest USD downside, particularly against the EUR and JPY. Although much of this outcome is priced in, the Senate result still leaves room for an incremental adjustment. EUR/USD in particular does look vulnerable to a short squeeze higher from a positioning standpoint.”
This has played out overnight and into London trading this morning. The fact that a Democratic Senate wasn’t fully priced has garnered the circa 0.5% move higher in EUR/USD and a corresponding move lower in the broader DXY.
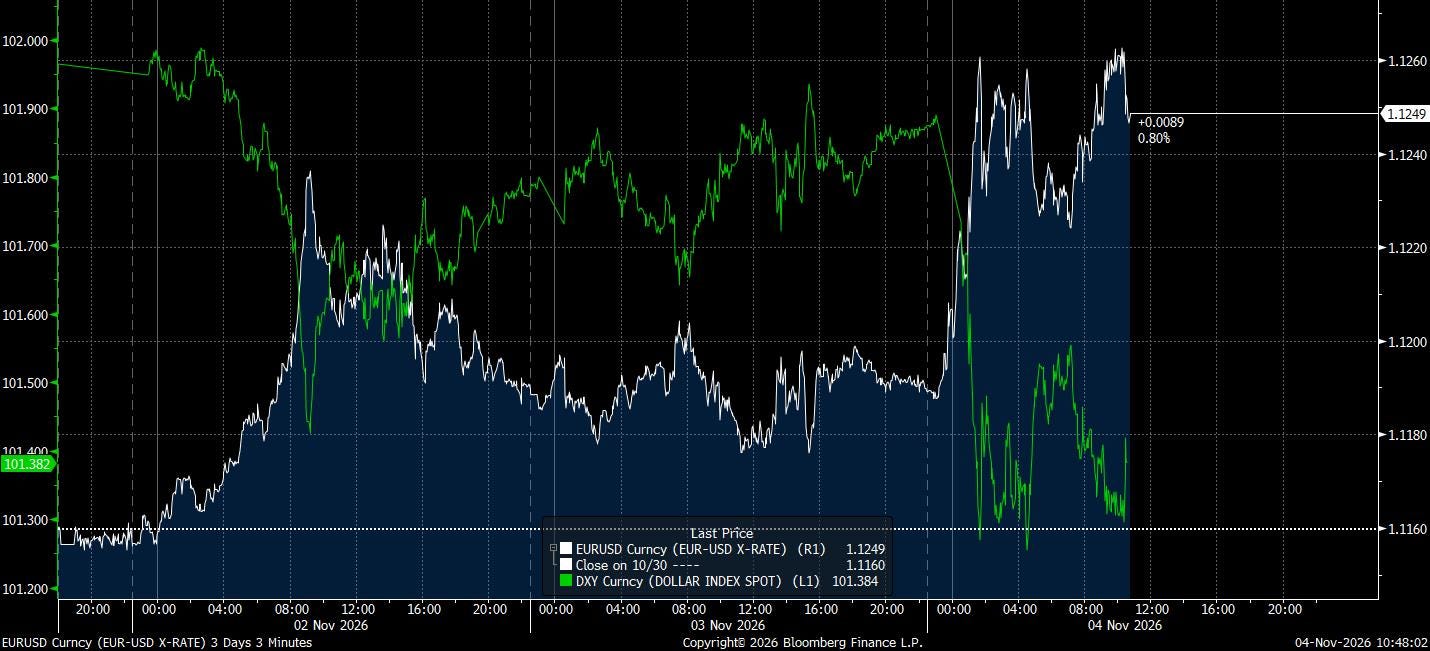
From here, most majors are consolidating against the greenback in the short term, with EUR/USD and USD/JPY the two pairs we’d flag as likely to continue squeezing due to existing skewed positioning.
Yet focus for FX quickly turns to Friday, where we get NFPs and related labour market data. This will act to provide the next stimulus for dollar flows, in a fairly binary NFP-style outcome.
The main pain trade come Friday close would be EUR/USD higher. The election result has moved the pair off recent lows, and the one-month EUR/USD risk reversals are quickly moving closer to neutral territory. If we get a disappointing data print on Friday, EUR/USD has room to run higher, given the Democrat win has already lit the spark.
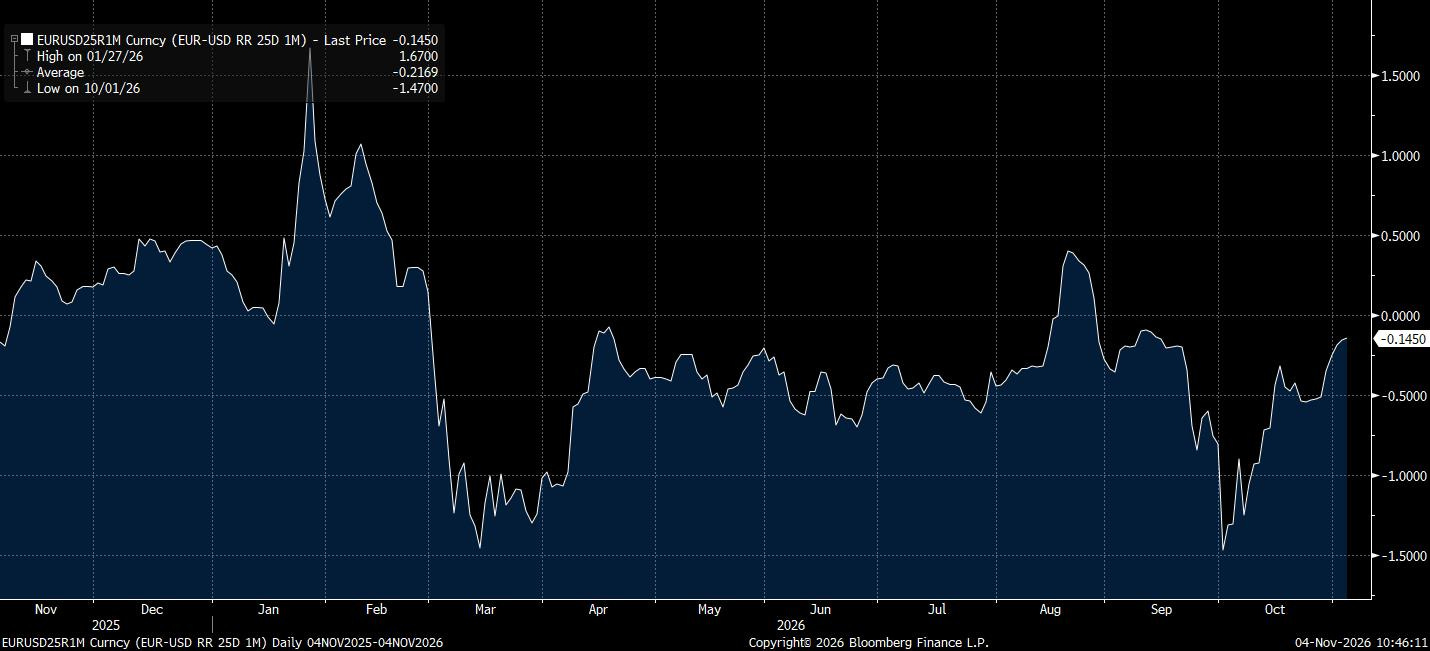
In the EM space, we don’t think the picture has changed much. Structurally weaker EM economies remain vulnerable, and volatile US long-term rates can weigh on EM assets even when the dollar is softer.
Equities and AI
The initial drop in stocks, bonds and the dollar in response to uncertainty over the US midterm elections showed markets’ view of the election as a de facto limit on AI investments.
The Democratic win of the House and Senate is a major blow to the Republicans and a clear rebuke of Trump, a president seen as a favourable tailwind for investment and growth. As equity indices and other assets have quickly retreated, the important question is whether they are permanently linked to a downward shift in the US growth outlook.