
Bonds are interesting again. That much is hard to dispute. Whether you think yields are attractive, bonds are the worst, or you’re simply on the sidelines watching yields rise without respite, it’s interesting.
Investors have been unimpressed, if not outright pained, for years by long-duration exposure. With yields at current levels, locking in coupons by holding bonds makes a reasonable argument. And if yields drop with slower growth or an unexpected move in inflation, bonds’ convexity becomes more enticing: take small losses, keep income, and reap big gains if the environment normalises.
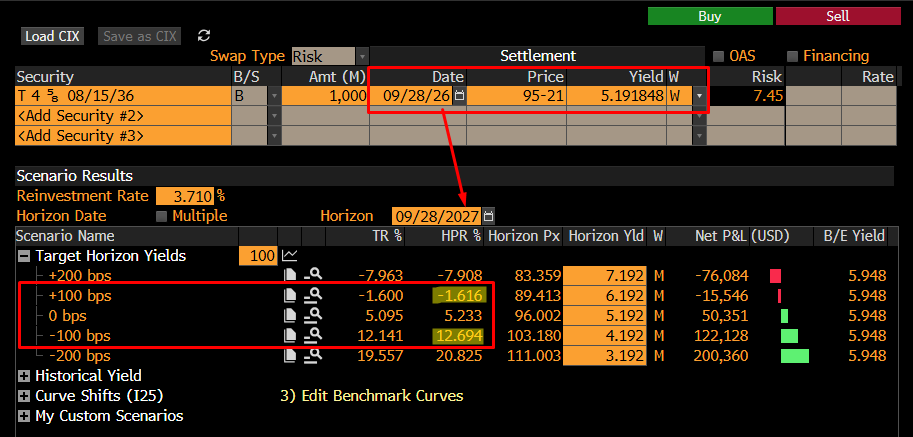
It’s an attractive setup, and many are weighing in on the conversation. At a 5.19% yield, the asymmetry on the 10-year may appeal to some: a 12.7% upside from a 100bp fall in yields versus a 1.6% downside from a 100bp rise over a one-year horizon (h/t Efficient Market Hype for the example below). Convexity is underappreciated by many, and one of the biggest reasons to own bonds here. However, the one-year payoff is not convexity alone. Carry, rolldown, and pull-to-par do much of the heavy lifting, particularly at a 5%+ starting yield.
There is also a low dollar convexity kicker here. Dollar prices of some low-coupon bonds have dipped below $50, effectively turning these instruments into quasi zero-coupon bonds with high convexity. In a substantial rally, the price return of these securities could outpace that of bonds trading closer to par.
What’s the Catalyst?
The question we’re asking is: what gets them there? An 8:1 return sounds nice on the surface until the probability attached to the upside case is considered. For duration to deliver the kind of returns we’re discussing here, something meaningful has to change.
For the rest of this note, we explore the catalysts that could drive yields lower, and where our conviction lies on receiving rates here or not. We also look at the negative ERP and why we don’t buy into the argument to abandon equities in favour of bonds.