
While the summer heat may finally be cooling off here in Europe, it’s hard to say the same is true in markets, especially in global debt.
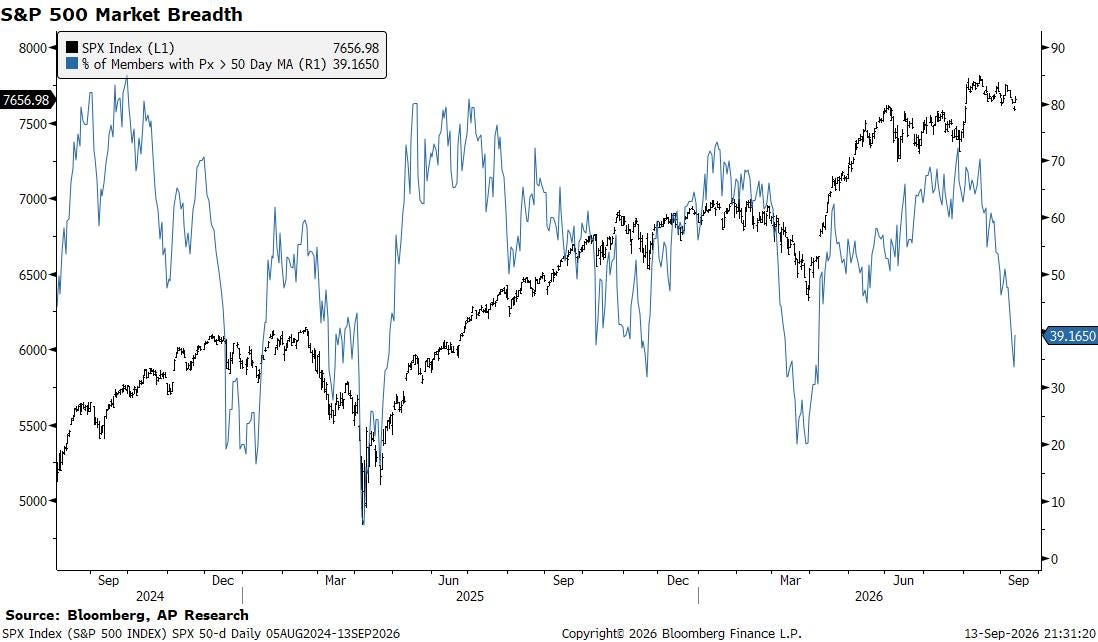
The S&P 500 fell in each of last week’s first three trading sessions, before a Friday rally pared the decline. The percentage of S&P 500 members above the 50-day moving average has declined rapidly over recent weeks. Just 39% of the 500-member gauge now trades above its average.
Brent crude and West Texas Intermediate gained 5.9% and 6.7% on Thursday, the highest closes since May 19. Energy was the only sector reliably in the green, while industrials and consumer discretionary bore the brunt of selling. But most of last week’s attention was on the Treasury market. US Treasury securities sold off across the curve, with the long end leading. The 30-year reached 5.373% on Thursday; the “highest since 2007” crowd was back as levels rose above those that prompted Bessent’s August intervention. The bear steepening reverses the Jackson Hole flattening and suggests markets are pricing in an inflation shock over a credibility restoration.
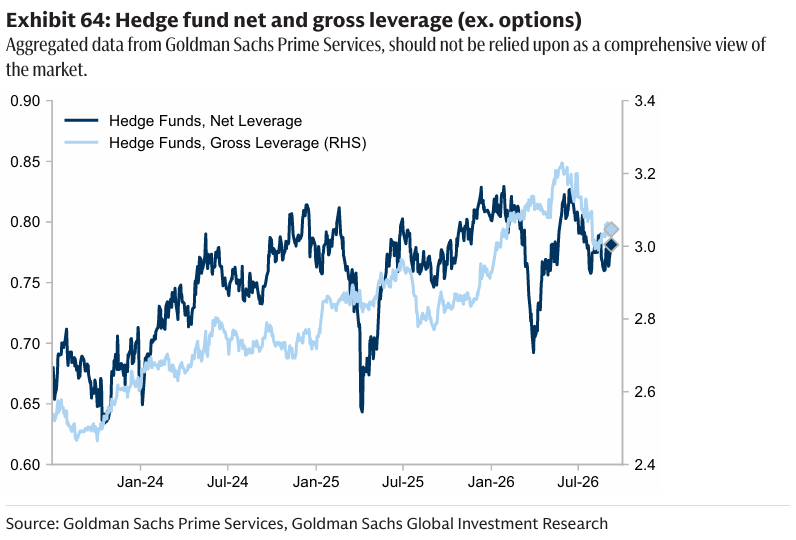
The rally did not change the rates picture, with a Federal Reserve hike very much fully expected. Goldman Sachs Prime Services sees net and gross hedge-fund leverage remaining well below this year’s highs.
The US dollar strengthened to a one-week high on Thursday, as oil-driven repricing at the front end did the work August data could not. Higher crude lifted US rate expectations faster than G-10 peers, making the dollar a passive beneficiary. That dynamic reverses quickly if the Fed hikes and signals it is done. Wednesday’s FOMC statement becomes more important for the currency than the decision itself. Precious metals took the other side, with gold selling off sharply as real yields pushed higher.
Behind the paywall, we highlight over views on global debt and state the case for our convictions in the short-term, as well as the implications for equity markets and a new rates trade following the ECB meeting.
Let’s get into the guide to trades moving markets, where things stand, and where they may be heading.
“Insufficient Funds”
“Elsewhere… One Hike, One Pause”
“Summary of House Views”
Insufficient Funds
“I am the house now.” — Sec. Bessent, September 9, 2026.
Of course, Bessent was talking to bears looking to short the yen against his interests, but it also symbolises his goals in the bond market. There’s a confidence, a swagger. Bessent believes he cannot lose.