
Bulls emerged from last week bruised as hot inflation and rising geopolitical tensions knocked out the support pillar for equities: the AI trade. Bears came out rejoicing. We’re sure many will be calling for Black Monday.
It was a volatile week. A hotter-than-expected inflation report fueled a risk-off move across all things AI, offsetting index gains in healthcare and consumer staples. It was the S&P’s worst day since July, ending a strong run of calm. Financing concerns returned, leading Coreweave to sell off 20% as its bonds soared to a 15% yield.
Memory stocks were also at the centre of last week’s pain after reports from China’s ChangXin Memory Technologies said it plans to introduce a denser server memory chip before the end of the year. That pushed Micron Technology down 3.9% and SanDisk down 6%, while optical-networking names Lumentum and Ciena fell 10% each. Selling spread to Asia on Tuesday, when South Korea’s Kospi sank 5.5%, and SK Hynix fell 10.1%.
Earnings season is well underway, so a few comments are in order. The big banks gave a mixed bag. Goldman Sachs reported a 72% jump in equities revenue, but surrendered early gains. Citigroup slid 5.6% as management guided to a decline of about 20% in fourth-quarter markets revenue, and JPMorgan Chase slipped after sharply reducing its share buyback. Overall, equities trading remained solid, but most other areas did not meet the high water marks of recent quarters.
Gasoline rose 9.1% in September and accounted for more than half of the monthly increase in headline CPI. Core goods prices rose by the most since January 2025, services excluding shelter and energy climbed 0.42%, and shelter rose 0.39%. Thursday’s PPI report added to the picture of energy costs feeding through the pipeline. The data showed annual PPI accelerated to 6.3% from a revised 5.6%.
Fedspeak offered little insight, largely expected given the new “low/no guidance” regime. Warsh declined to comment on October’s meeting, while the Fed’s Hammock said policy is not yet restrictive enough to return inflation to its 2% target.
US Treasury bonds rallied at the long end even as inflation data ran hot, marking a tough week for those biased to a bull steepener. The 10-year rose to around 5.30% after Wednesday’s CPI print, then closed at 5.19%. It then fell 10bps to 5.09% on Thursday, its lowest close since September 22, as the selloff in AI shares and Asian equities drove demand for havens. Bonds finally acted like bonds. Data showed liquidations in UST futures across tenors, as short covering drove much of the rally in the latter part of the week.
The dollar rallied after Wednesday’s CPI report but couldn’t hold gains as Treasury yields, the core of recent strength, retreated. The dollar index hit its highest level since last April before fading by week’s end. Realised volatility remains relatively subdued, with price action in FX markets driven more by other assets, particularly the long end of the UST curve.
On a final note for last week’s roundup, cars now fly. Love him or hate him, Elon’s roadmap seems decades ahead of everyone else. It’s rather spectacular to watch.
The week ahead will be closely watched after last week’s action. So, let’s get into the guide to trades moving markets, where things stand, and where they may be heading.
“Rundown of Equity Themes”
“Markets Are Energy-Pilled”
“Summary of House Views”
Enjoy 7 days of complimentary access to AP Research. Unlock this report, our full research archive, and our latest market insights with a free 7-day trial. Start your free trial here.
Rundown of Equity Themes
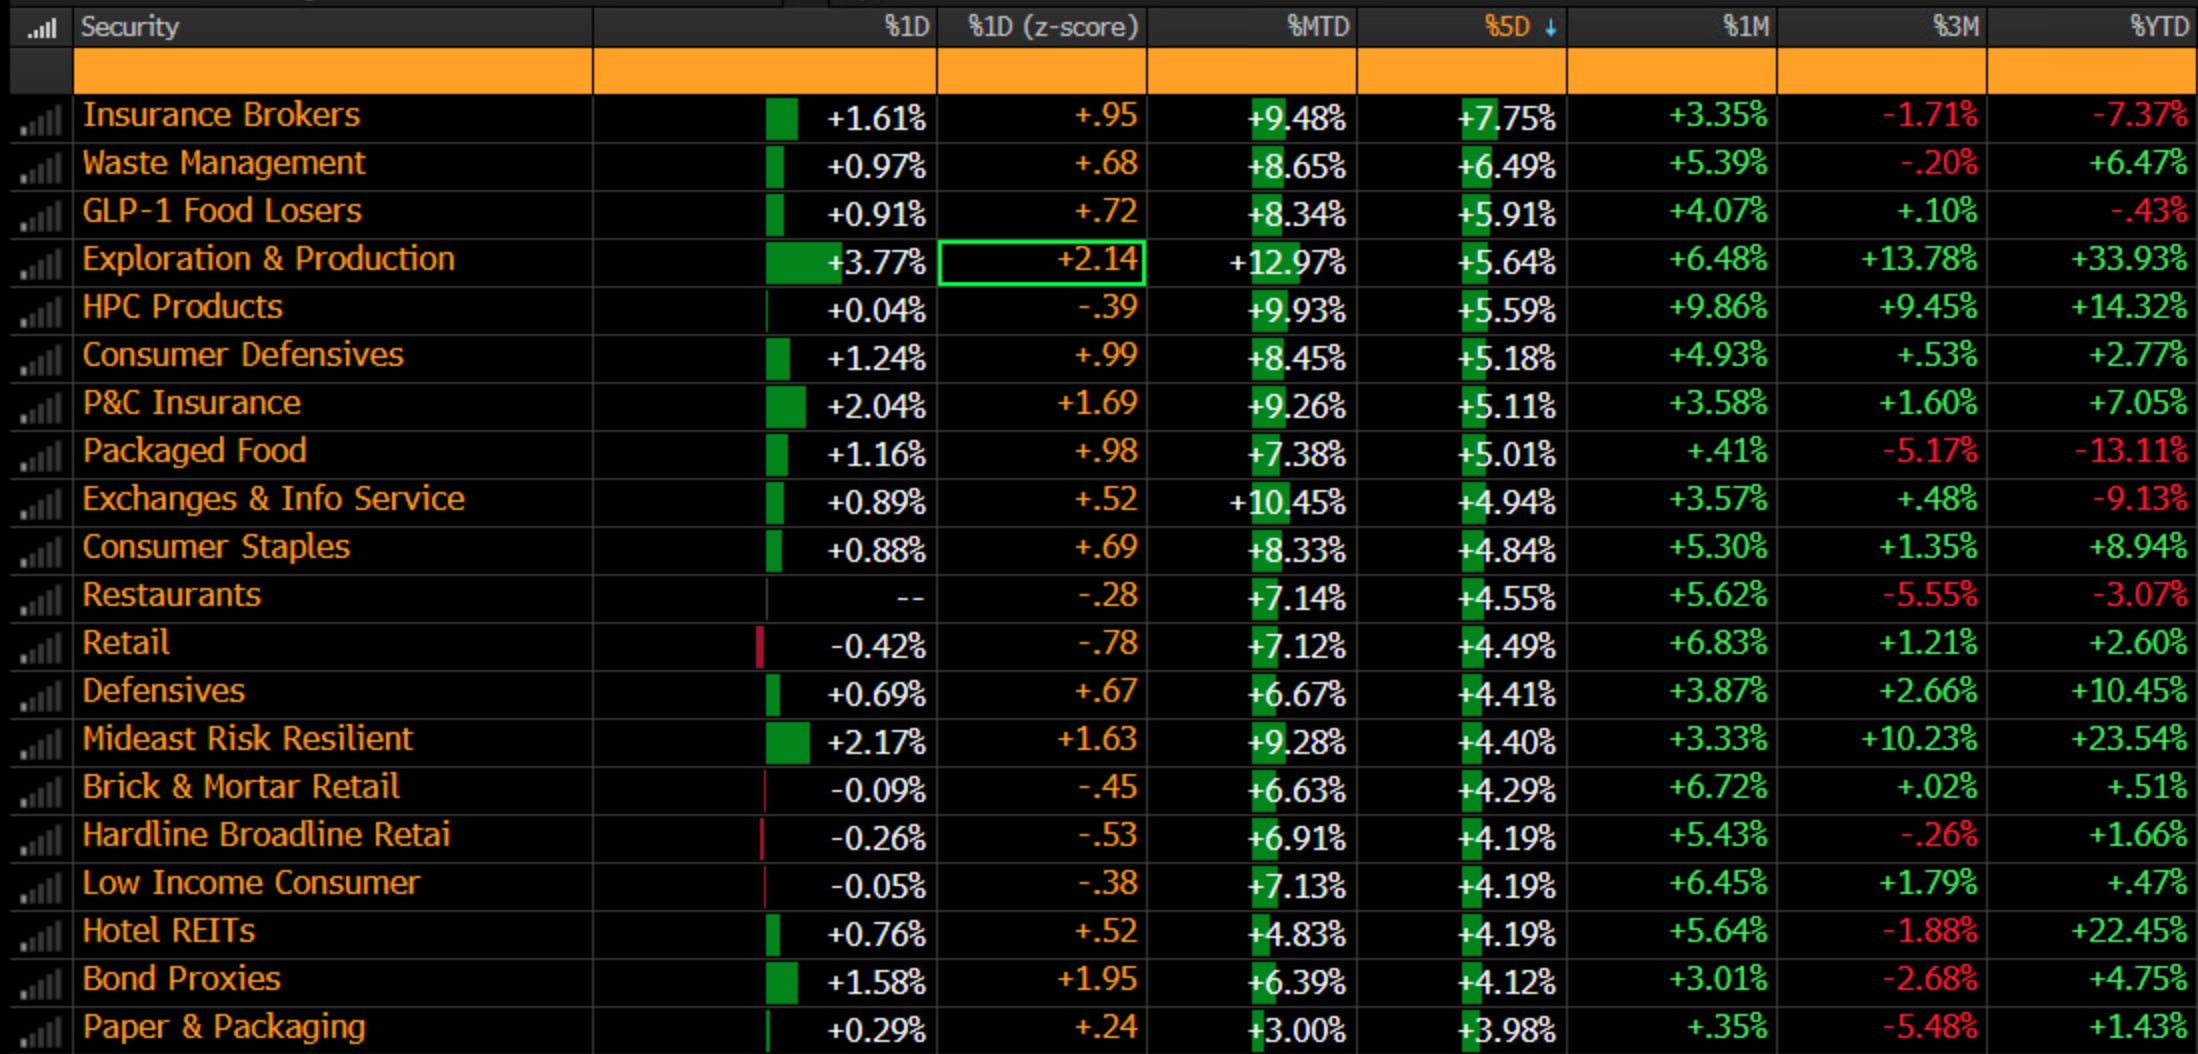
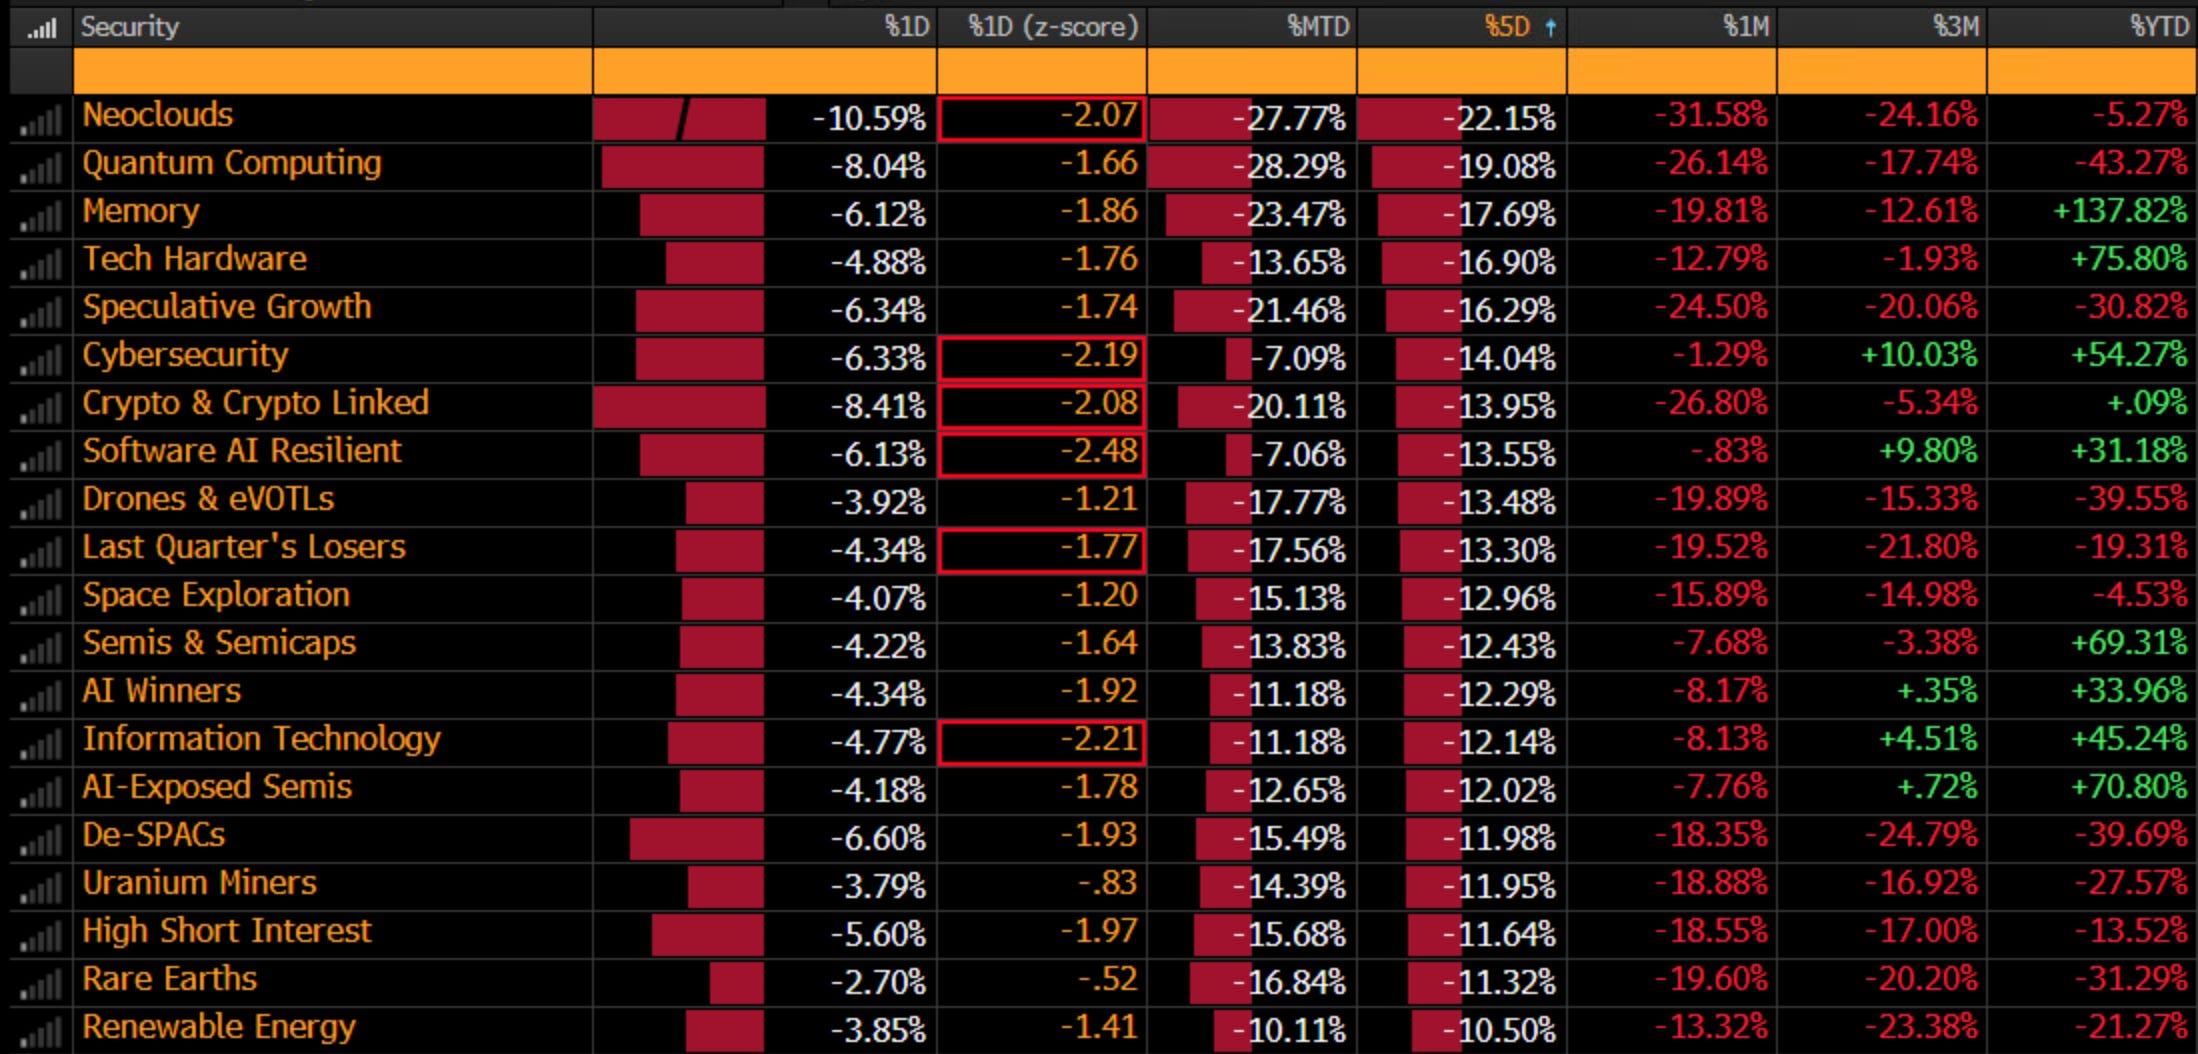
While attention has recently focused on yields, it most certainly returned to equities last week, which makes this the start of our Monday memo.