
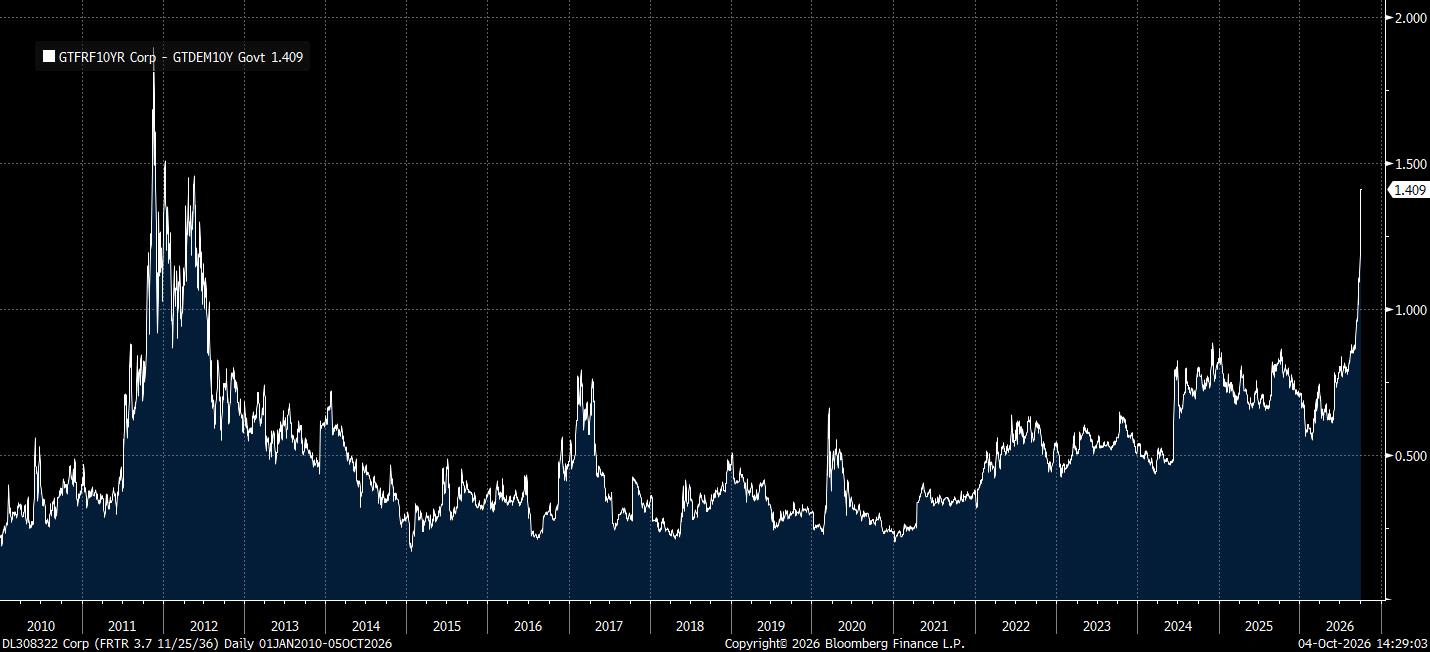
Last week, we called bonds undiplomatic. That now looks generous.
What started as a continuation of the most recent trend stretched towards, dare we say, panic (at least in the headlines). Sovereigns with idiosyncratic risks, such as France, fared even worse, as the OAT-Bund spread soared toward 150bps. We had identified this risk in early September (“Qui paie ses dettes s’enrichit”), and we took exposure to the spread widening. After a move from 87bps to 120bps, we took this trade off the books, and in true market fashion, that provided the next leg higher as the spread moved to 150bps just 48 hours later. C’est la vie. One thing is certain: rising yields have found Europe’s weak spot.
Equities stayed resilient. After all, this is a growth-led pressure in bonds, which benefits equities. Rate-sensitive sectors, such as financials, bore the brunt of any selling, finishing September with the second-worst return in 15 years. Technology again provided the main support for the broader market. Semiconductor and software stocks helped the S&P 500 regain more than 60 points off its lows on Thursday and snap a three-day losing streak. Retail stayed under pressure as Nike sank to a 13-year low after poor guidance after the bell on Thursday, off 81% from November 2021 highs. Nike’s “Just Do It” mantra is looking less convincing when whatever it did clearly didn’t work.
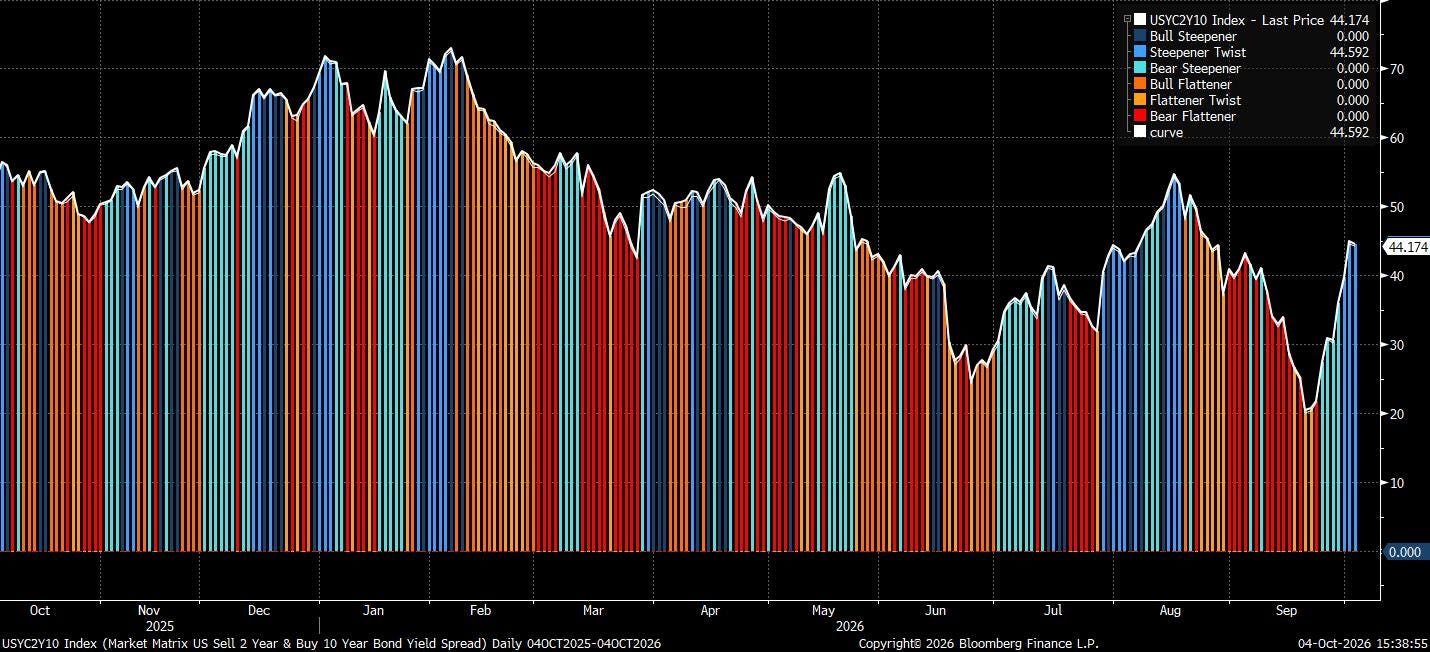
As for economic data last week, Friday’s payrolls report showed employers added just 29k jobs, and traders have largely priced out a hike in October. Still, long-end UST yields kept climbing even as rate-hike odds fell, leading to a strong steepening in the curve by week’s end.
Regarding US-Iran and oil, a stalemate provided minimal information and mixed signals for markets. While stocks pared steeper declines on a report that President Donald Trump was willing to give Iran sanctions relief, Iranian officials expressed pessimism about reaching a deal to end hostilities. For now, oil remains off recent highs, with no clear sign that tensions are easing. Yields’ minimal reaction to last week’s drop is a fair indication that oil is by no means the driver of pressure right now.
The dollar remains well supported as rate differential remained favourable. This was evident in EUR/USD, as French budget issues kept downward pressure on the pair and ECB rate hikes were priced out. As our APFX team noted on Friday, “we believe the second-order move [of French fiscal risk] will be felt in lower ECB pricing expectations for 2027.”
That wraps up our takeaways from what was a pronounced week in markets. Let’s get into the guide to trades moving markets, where things stand, and where they may be heading.
“Contagion Aware”
“Getting Bulled Up”
“Summary of House Views”
Just a quick note before we move into the rest of this memo: we joined Prometheus Research last Wednesday to talk all things FX and macro. We thoroughly enjoyed the discussion and wanted to share a link to the audio for anyone interested.

Contagion Aware
The biggest driver of markets this week will be a continuation of the yield story. Maybe the biggest worry on markets’ minds will be contagion risk, with memories of Europe’s debt crisis 15 years ago still fresh.